

PRM Certification 8008 Dumps | Updated Sep 21, 2021 - PassExamDumps
Master 2021 Latest The Questions PRM Certification and Pass 8008 Real Exam!
NEW QUESTION 11
Which of the following objectives are targeted by rating agencies when assigning ratings:
I. Ratings accuracy
II. Ratings stability
III. High accuracy ratio (AR)
IV. Ranked ratings
- A. II and III
- B. I and II
- C. I, II and III
- D. III and IV
Answer: B
Explanation:
Explanation
Rating agencies target both accuracy and stability when they assign ratings. These two objectives can sometimes conflict, so a balance needs to be struck between the two. Rating agencies do not target any particular 'accuracy ratio' or rankings. Therefore Choice 'c' is the correct answer.
NEW QUESTION 12
For a hypotherical UoM, the number of losses in two non-overlapping datasets is 24 and 32 respectively. The Pareto tail parameters for the two datasets calculated using the maximum likelihood estimation method are 2 and 3. What is an estimate of the tail parameter of the combined dataset?
- A. 2.57
- B. Cannot be determined
- C. 2.23
- D. 0
Answer: A
Explanation:
Explanation
For a number of processes, including many in finance, while a distribution such as the normal distribution is a good approximation of the distribution near the modal value of the variable, the same normal distribution may not be a good estimate of the tails. For this reason, the Pareto distribution is one of the distributions that is often used to model the tails of another distribution. Generally, if you have a set of observations, and you discard all observations below a threshold, you are left with what are called 'exceedances'. The threshold needs to be reasonably far out in the tail. If from each value of the exceedances you subtract the threshold value, the resulting dataset is estimated by the generalized Pareto distribution.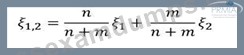
The Pareto distribution has a 'shape parameter'. The average of two Pareto distributions with tail parameters 1 and 2 ( is a Greek character, pronounced as 'sai' (saa-eee)), is the weighted average of 1 and 2 with weights proportional to the number of observations in the datasets underlying the distributions.
NEW QUESTION 13
If the cumulative default probabilities of default for years 1 and 2 for a portfolio of credit risky assets is 5% and 15% respectively, what is the marginal probability of default in year 2 alone?
- A. 10.53%
- B. 15.79%
- C. 11.76%
- D. 10.00%
Answer: A
Explanation:
Explanation
One way to think about this question is this: we are provided with two pieces of information: if the portfolio is worth $100 to start with, it will be worth $95 at the end of year 1 and $85 at the end of year 2. What it is asking for is the probability of default in year 2, for the debts that have survived year 1. This probability is
$10/$95 = 10.53%. Choice 'b' is the correct answer.
Note that marginal probabilities of default are the probabilities for default for a given period, conditional on survival till the end of the previous period. Cumulative probabilities of default are probabilities of default by a point in time, regardless of when the default occurs. If the marginal probabilities of default for periods 1, 2... n are p1, p2...pn, then cumulative probability of default can be calculated as Cn = 1 - (1 - p1)(1-p2)...(1-pn). For this question, we can calculate the probability of default for year 2 as [1 - (1 - 5%)(1 - 10.53%)] = 15%.
NEW QUESTION 14
Which of the following assumptions underlie the 'square root of time' rule used for computing VaR estimates over different time horizons?
I. the portfolio is static from day to day
II. asset returns are independent and identically distributed (i.i.d.)
III. volatility is constant over time
IV. no serial correlation in the forward projection of volatility
V. negative serial correlations exist in the time series of returns
VI. returns data display volatility clustering
- A. I, II, V and VI
- B. III, IV, V and VI
- C. I, II, III and IV
- D. I and II
Answer: C
Explanation:
Explanation
The square root of time rule can be used to convert, say a 1-day VaR to a 10-day VaR, by multiplying the known number by the square root of time to get the VaR over a different time horizon. However, there are key assumptions that underlie the application of this rule, and statements I to IV correctly state those assumptions.
Statements V and VI are not correct, because the application of the square root of time rule requires the absence of serial correlations, and also the absence of volatility clustering (ie independence). Therefore Choice
'c' is the correct answer.
The square root of time rule is also applied to convert volatility or standard deviation for one period to the volatility for a different time period. Remember that VaR is just a multiple of volatility, and therefore the assumptions that apply to the square root of time rule for VaR also apply to the same rule when used in the context of volatilities or standard deviation.
NEW QUESTION 15
When doing stress tests based on historical scenarios, if no appropriate historical scenarios exist for a security, it is most INAPPROPRIATE to:
- A. Estimate a shock factor based on other instruments that might be considered as proxies for such a security
- B. Estimate a shock factor based upon extrapolation
- C. Leave the position unshocked
- D. Estimate a shock factor based upon interpolation
Answer: C
Explanation:
Explanation
Where a historical shock factor does not exist for a security, for example because the security is new or was only thinly traded earlier, or because a particular emerging market was immature at the time of the historical scenario being considered, it is inappropriate to leave the position unshocked. By and large, the general rule to be followed when carrying out stress testing is to leave no position unshocked. Therefore Choice 'b' is the correct answer.
Choice 'd', Choice 'a' and Choice 'c' all represent valid approaches to estimating a shock factor in such cases.
NEW QUESTION 16
Which of the following statements are correct?
I. A reliance upon conditional probabilities and a-priori views of probabilities is called the 'frequentist' view II. Knightian uncertainty refers to things that might happen but for which probabilities cannot be evaluated III. Risk mitigation and risk elimination are approaches to reacting to identified risks IV. Confidence accounting is a reference to the accounting frauds that were seen in the past decade as a reflection of failed governance processes
- A. II and III
- B. I and IV
- C. All of the above
- D. II, III and IV
Answer: A
Explanation:
Explanation
In statistics, which is relevant to risk management, a distinction is often drawn between 'frequentists' and
'Bayesians'. Frequentists rely upon data to draw conclusions as to probabilities. Bayesians consider conditional probabilities, ie, take into account what things are already known, and inject sometimes subjective a-priori probabilities into the calculations. Statement I describes Bayesians, and not frequentists. In reality however, the difference is merely academic. Risk managers use whichever technique best applies to the given situation without making it about ideology.
The difference between 'Knightian uncertainty' and 'Risk' is similarly academic. Knightian uncertainty refers to risk that cannot be measured or calculated. 'Risk' on the other hand refers to things for which past data exists and calculations of exposure can be made. To give an example in the context of the financial world, the risk from a pandemic creating systemic failures from a failure of payment and settlement systems and the like is
'Knightian uncertainty', but the market risk from equity price movements can be modeled (albeit with limitations) and is calculable. Statement II is therefore correct.
Once a risk is identified, it can be mitigated, accepted, avoided or eliminated, or transferred by way of insurance. Therefore statement III is correct.
Confidence accounting is a conceptual idea that suggests that accounting statements make reference to ranges as opposed to point estimates in financial statements. For example, instead of saying that the pension obligation is $xx million, the company should say the pension obligation is in a range of $xx m - $yy m with a certain confidence level. Statement IV is therefore inaccurate.
NEW QUESTION 17
Which of the following statements is correct?
- A. Market liquidity risk is idiosyncratic while funding liquidity risk is not
- B. Market liquidity risks present themselves in the form of higher bid offer spreads
- C. Dynamic simulations of liquidity needs require an assumption of counterparty risk remaining constant
- D. Funding liquidity risks present themselves in the form of an adverse market impact on prices from a trade
Answer: B
Explanation:
Explanation
Simulations of liquidity needs can be of various types: historical simulations, where the current positions are subjected to the kind of liquidity shocks experienced in the past; static simulations, where a static view of current positions, counterparty credit position, and the business is considered; and dynamic simulations where all factors are dynamically changed including counterparty credit standing, changes to the current portfolio and behavioural aspects of the business. Choice 'b' is incorrect as dynamic simulations require no such assumptions.
Liquidity risk is often thought of in terms of market liquidity risk and funding liquidity risk. Market liquidity risk relates to the the liquidity for a particular type of asset drying up. For example, during the 2007-2009 crisis a large number of corporate bonds and structured products became extremely illiquid. Market liquidity risk manifests itself in the form of higher bid offer spreads, higher pricde impact, and a reduction in the normal market size (ie, the 'normal' size of a trade for which a dealer quote is valid for). Therefore Choice 'd' is correct. Similarly, Choice 'a' is incorrect as adverse price impact results from market liquidity risk and not funding liquidity risk.
Market liquidity risk applies to the entire market and all its participants. It is not idiosyncratic. Therefore Choice 'c' is incorrect too. Funding liquidity risk on the other hand applies to an individual institution that is under liquidity stress in the sense of not being able to meet its obligations such as margin or collateral calls because of a lack of liquid assets. Thus it is funding liquidity that is idiosyncratic. Market liquidity risk often leads to funding liquidity risks materializing as firms are unable to get to the funds they were relying upon due to assets becoming illiquid.
NEW QUESTION 18
The sum of the stand alone economic capital of all the business units of a bank is:
- A. unrelated to the economic capital for the firm as a whole
- B. more than the economic capital for the firm as a whole
- C. less than the economic capital for the firm as a whole
- D. equal to the economic capital for the firm as a whole
Answer: B
Explanation:
Explanation
Economic capital is sub-additive, ie, because of the correlation being less than perfect between the risks of the different business units, the total economic capital for the firm will be less than the sum of the EC for the individual business units. Therefore Choice 'b' is the correct answer.
In practice, correlations are difficult to estimate reliably, and banks often use estimates and corroborate their capital calculations with reference to a number of data points.
NEW QUESTION 19
Which of the following statements is true in respect of different approaches to calculating VaR?
I. Linear or parametric VaR does not take correlations into account
II. For large portfolios with little or no optionality or other non-linear attributes, parametric VaR is an efficient approach to calculating VaR III. For large portfolios with complex sources of risk and embedded optionalities, the full revaluation method of calculating VaR should be preferred IV. Delta normal local revaluation based VaR is suitable for fixed income and option portfolios only
- A. II and III
- B. I and IV
- C. III only
- D. I, II, III and IV
Answer: A
Explanation:
Explanation
This question is different in that it uses terminology you will not find in the PRMIA handbook. Yet it is important to understand these as there may be a question based on this slightly different terminology. (It is only the terminology that is different, the concepts are the same.) If you read the PRMIA handbook, there are three methods of calculating VaR: Analytical or parametric, historical simulation and Monte Carlo simulations. There is one more way of categorizing the methods of calculating VaR, and these are as follows:
1. Local valuation: This refers to analytical or parametric VaR. This relies upon a neat statistical formula to calculate VaR and assumes a normal distribution. It also relies upon a known covariance matrix between the different components of VaR. Local valuation based VaR is further subdivided into two types:
a. Linear VaR: Linear VaR is calculated assuming the portfolio is linear, and its value changes just based upon the delta of the portfolio. In such cases, once a change (eg, in stock values) is known, that change is multiplied by the delta alone to get the VaR. Second order effects, such as gamma or convexity are ignored.
b. Non-linear VaR: Non linear analytical VaR is calculated using both delta and the second derivative, ie gamma or the convexity. This is more accurate if the portfolio is non-linear.
The key thing about 'local revaluation' VaR is that it does not require us to reprice or completely value all instruments in the portfolio. All we have to know is the delta (or the gamma and convexity as well) and multiply that with the number of standard deviations of change in the risk factor that we are interested in. So if we are considering a bond, we don't have to recalculate the new value of the bond as we can just use the delta.
This can be a significant computational advantage for a large financial institution where there may be a large number of positions.
2. Full revaluation: This refers to a VaR method where the asset in question is fully repriced based on the new value of the risk factor - and this includes both historical and Monte Carlo based VaR methods.
Local revaluation, or analytical method based VaR is computationally easier to calculate, specially if based on just the delta-normal method (ie ignoring second order effects from convexity or gamma). But it will give incorrect results if the portfolio includes substantial non-linearity or other complexities. The full revaluation methods will always give the correct results, but they can be computationally difficult to arrive at.
Statement I is completely inaccurate - local revaluation methods do take correlations into account through the correlation or covariance matrices. Statement IV is false too - the 'delta normal' VaR refers to Var calculations based upon just the delta and do not account for the convexity or optionality. Statements II and III are correct.
Therefore Choice 'c' is the correct answer.
NEW QUESTION 20
When compared to a medium severity medium frequency risk, the operational risk capital requirement for a high severity very low frequency risk is likely to be:
- A. Higher
- B. Unaffected by differences in frequency or severity
- C. Lower
- D. Zero
Answer: D
Explanation:
Explanation
High frequency and low severity risks, for example the risks of fraud losses for a credit card issuer, may have high expected losses, but low unexpected losses. In other words, we can generally expect these losses to stay within a small expected and known range. The capital requirement will be the worst case losses at a given confidence level less expected losses, and in such cases this can be expected to be low.
On the other hand, medium severity medium frequency risks, such as the risks of unexpected legal claims,
'fat-finger' trading errors, will have low expected losses but a high level of unexpected losses. Thus the capital requirement for such risks will be high.
It is also worthwhile mentioning high severity and low frequency risks - for example a rogue trader circumventing all controls and bringing the bank down, or a terrorist strike or natural disaster creating other losses - will probably have zero expected losses & high unexpected losses but only at very high levels of confidence. In other words, operational risk capital is unlikely to provide for such events and these would lie in the part of the tail that is not covered by most levels of confidence when calculating operational risk capital.
Note that risk capital is required for only unexpected losses as expected losses are to be borne by P&L reserves. Therefore the operational risk capital requirements for a low severity high frequency risk is likely to be low when compared to other risks that are lower frequency but higher severity.
Thus Choice 'c' is the correct answer.
NEW QUESTION 21
A bank's detailed portfolio data on positions held in a particular security across the bank does not agree with the aggregate total position for that security for the bank. What data quality attribute is missing in this situation?
- A. Data extensibility
- B. Data completeness
- C. Auditability
- D. Data integrity
Answer: D
Explanation:
Explanation
The term 'data quality' has multiple elements, ie, data in order to be considered of a high quality must have multiple attributes such as completeness, timeliness, auditability etc. Because this is not an exact science, every expert or text book will have a different view of what goes into data quality. For our purposes however, we will stick to what the PRMIA study material specifies, and according to the study material the following are the elements that can be considered attributes that make for quality data:
1. Integration
2. Integrity
3. Completeness
4. Accessibility
5. Flexibility
6. Extensibility
7. Timeliness
8. Auditability
I am not going to describe each of these here as that would be repetitive of the study material, but suffice it to say that the break-down of a number into its constituents should tie to the aggregate total. If that is not true, then the data lacks integrity - and therefore Choice 'b' is the correct answer. The other choices address other aspects of data quality but not this, and therefore are not correct.
NEW QUESTION 22
The estimate of historical VaR at 99% confidence based on a set of data with 100 observations will end up being:
- A. the extrapolated returns of the last 1.64 observations
- B. the weighted average of the top 2.33 observations
- C. the worst single observation in the data set
- D. None of the above
Answer: C
Explanation:
Explanation
The VaR in this case will be the top quintile of observations. In this case, since there are exactly 100 observations, this would mean the worst return would become the VaR. Therefore Choice 'b' is the correct answer. Choice 'a' and Choice 'c' make no sense. This highlights that at higher confidence levels, fewer and fewer observations impact the VaR if we are using historical simulation based VaR.
NEW QUESTION 23
A bank evaluates the impact of large and severe changes in certain risk factors on its risk using a quantitative valuation model. Which of the following best describes this exercise?
- A. Stress testing
- B. Sensitivity analysis
- C. Simulation
- D. Scenario analysis
Answer: D
Explanation:
Explanation
It is important to note the difference between sensitivity analysis and stress testing. Sensitivity analysis applies to measuring the effect of changes on the outputs of a model by varying the inputs - generally one input at a time.
In scenario analysis, a number of variables may be changed at the same time to see the impact on the dependent variable. For example, a bank may measure the changes in the value of its mortgage portfolio by varying its assumptions on prepayment expectations, interest rates and other factors, using its modeling software or application. The changes in the inputs may or may not relate to integrated real world situations that may arise. Sensitivity analysis is purely a quantitative exercise, much like calculating the delta of a portfolio.
A stress test may include shocks or large changes to input parameters but it does so as part of a larger stress testing programme that generally considers the interaction of risk factors, past scenarios etc. At its simplest, a stress test may be no different from a sensitivity analysis exercise, but that is generally not what is considered a stress test at large financial institutions.
A stress test may consider multiple scenarios, for example one scenario may include the events witnessed during the Asian crisis, another may include the events of the recent credit crisis. Simulation generally refers to a Monte Carlo or historical simulation, and is often a more limited exercise.
The exercise described in the question is the closest to a scenario analysis, therefore Choice 'c' is the correct answer.
It is important to note that all of the choices referred to in this question are related to each other, and the boundaries between them tend to be fuzzy. At what point does a complex sensitivity analysis start resembling a scenario, or a stress test can always be debatable, but such a debate would be more about the symantics than be of any practical use.
NEW QUESTION 24
A bank extends a loan of $1m to a home buyer to buy a house currently worth $1.5m, with the house serving as the collateral. The volatility of returns (assumed normally distributed) on house prices in that neighborhood is assessed at 10% annually. The expected probability of default of the home buyer is 5%.
What is the probability that the bank will recover less than the principal advanced on this loan; assuming the probability of the home buyer's default is independent of the value of the house?
- A. More than 1%
- B. More than 5%
- C. Less than 1%
- D. 0
Answer: C
Explanation:
Explanation
The bank will not be able to recover the principal advanced on this loan if both the home buyer defaults, and the house value falls to less than $1m, ie the price moves adversely by more than $500k, which is
$-500k/$150k = -3.33. (Note that 150k is the 1 year volatility in dollars, ie $1.5m * 10%).
The probability of both these things happening together is just the product of the two probabilities, one of which we know to be 5%. The other is also certainly a small number, and intuitively it is clear that the probability of both the things happening together will be less than 1%.
For a more precise answer, we can calculate the probability of the house price falling by 3.33 standard deviations by calculating the area under the standard normal curve to the left of -3.33. This indeed is a very small number (actually equal to NORMSINV(-3.33)=0.00043), which when multiplied by the probability of default of the home buyer at 5% is certainly going to be less than 1%. Therefore Choice 'b' is the correct answer.
NEW QUESTION 25
Which of the following steps are required for computing the total loss distribution for a bank for operational risk once individual UoM level loss distributions have been computed from the underlhying frequency and severity curves:
I. Simulate number of losses based on the frequency distribution
II. Simulate the dollar value of the losses from the severity distribution III. Simulate random number from the copula used to model dependence between the UoMs IV. Compute dependent losses from aggregate distribution curves
- A. I and II
- B. All of the above
- C. None of the above
- D. III and IV
Answer: A
Explanation:
Explanation
A recap would be in order here: calculating operational risk capital is a multi-step process.
First, we fit curves to estimate the parameters to our chosen distribution types for frequency (eg, Poisson), and severity (eg, lognormal). Note that these curves are fitted at the UoM level - which is the lowest level of granularity at which modeling is carried out. Since there are many UoMs, there are are many frequency and severity distributions. However what we are interested in is the loss distribution for the entire bank from which the 99.9th percentile loss can be calculated. From the multiple frequency and severity distributions we have calculated, this becomes a two step process:
- Step 1: Calculate the aggregate loss distribution for each UoM. Each loss distribution is based upon and underlying frequency and severity distribution.
- Step 2: Combine the multiple loss distributions after considering the dependence between the different UoMs. The 'dependence' recognizes that the various UoMs are not completely independent, ie the loss distributions are not additive, and that there is a sort of diversification benefit in the sense that not all types of losses can occur at once and the joint probabilities of the different losses make the sum less than the sum of the parts.
Step 1 requires simulating a number, say n, of the number of losses that occur in a given year from a frequency distribution. Then n losses are picked from the severity distribution, and the total loss for the year is a summation of these losses. This becomes one data point. This process of simulating the number of losses and then identifying that number of losses is carried out a large number of times to get the aggregate loss distribution for a UoM.
Step 2 requires taking the different loss distributions from Step 1 and combining them considering the dependence between the events. The correlations between the losses are described by a 'copula', and combined together mathematically to get a single loss distribution for the entire bank. This allows the 99.9th percentile loss to be calculated.
NEW QUESTION 26
Which of the following are true:
I. Delta hedges need to be rebalanced frequently as deltas fluctuate with fluctuating prices.
II. Portfolio managers are right to focus on primary risks over secondary risks.
III. Increasing the hedge rebalance frequency reduces residual risks but increases transaction costs.
IV. Vega risk can be hedged using options.
- A. I, II, III and IV
- B. I, II and III
- C. I and II
- D. II, III and IV
Answer: A
Explanation:
Explanation
Delta is non-linear with respect to prices for a number of securities such as bonds, options and other derivatives. It changes with changes in prices, and any hedge initially undertaken becomes quickly mismatched. Therefore delta hedges need to be managed quite actively and kept up-to-date. Therefore I is true.Primary risks comprise most of the risk in a position, and therefore portfolio managers are right to focus on them over secondary risks. Therefore II is true.The greater the hedge rebalance frequency, the lower is the hedge mismatch at any point in time, and therefore residual risks would be lower. However, rebalancing hedges requires rebalance trades to be done, and these involve transaction costs. Generally, a reasonable balance needs to be struck between the frequency of rebalances (a lower frequency increases residual risk, but this residual risk is not directionally biased) and the costs of rebalancing. III is correct.Vega risk is the risk arising due to changes in prices due to changes in volatility. Options carry vega risk. Therefore any hedges against vega risks can only be obtained using other options positions. (Vega risk may also be hedged using other volatility based products, eg an OTC volatility swap, or a VIX futures type product.)
NEW QUESTION 27
Which of the following statements is true in relation to a normal mixture distribution:
I. Normal mixtures represent one possible solution to the problem of volatility clustering II. A normal mixture VaR will always be greater than that under the assumption of normally distributed returns III. Normal mixtures can be applied to situations where a number of different market scenarios with different probabilities can be expected
- A. II and III
- B. I, II and III
- C. I and II
- D. III
Answer: D
Explanation:
Explanation
Normal mixtures address fat or heavy tails, not volatility clustering. Therefore statement I is not correct.
Statement II is not correct. Where VaR is calculated at low levels of confidence, VaR based on normal mixtures may be lower than that under a normal assumption. This is no different than for other fat tailed distributions.
Statement III is correct. In situations where multiple market scenarios can unfold with a given probability, and each scenario is normal, we can express the result with a normal mixture where the underlying normal distributions have the probabilities of the different scenarios.
NEW QUESTION 28
Which of the following statements are true?
I. Retail Risk Based Pricing involves using borrower specific data to arrive at both credit adjudication and pricing decisions II. An integrated 'Risk Information Management Environment' includes two elements - people and processes III. A Logical Data Model (LDM) lays down the relationships between data elements that an organization stores IV. Reference Data and Metadata refer to the same thing
- A. II and IV
- B. All of the above
- C. I, II and III
- D. I and III
Answer: D
Explanation:
Explanation
Statement I is correct. Retail Risk Based Pricing (RRBP) involves the use of borrower specific data (such as FICO scores, average balances etc) to arrive at credit decisions. These 'retail' credit decisions may include decisions on whether to grant a line of credit, a mortgage, issue a credit card, or any of the various other retail activities a bank may be dealing with. At the same time, this data can also be used to price the product, in addition to providing a yes or no credit decision so that risky borrowers are charged more than less risky borrowers.
Statement II is not correct, because an integrated Risk Information Management Environment includes three elements - people, processes and technology (and not just people and processes).
Statement III is correct. An LDM is a blue print of an organization's data, and describes the relationships between the various data elements.
Statement IV is not correct because reference data and metadata are not the same thing. Reference data refers to relatively static data, such as customer name (while actual transactions may not be so static). Metadata refers to data about data, and is stored in a data dictionary.
Therefore Choice 'b' is the correct answer and the rest are incorrect.
NEW QUESTION 29
A loan portfolio's full notional value is $100, and its value in a worst case scenario at the 99% level of confidence is $65. Expected losses on the portfolio are estimated at 10%. What is the level of economic capital required to cushion unexpected losses?
- A. 0
- B. 1
- C. 2
- D. 3
Answer: C
Explanation:
Explanation
Expected value = $90 ($100 - 10%)
Value at 99% confidence level = $65
Therefore economic capital required at this level of confidence = $90 - $65 = $25.
Choice 'a' is the correct answer, the other choices are not.
(We can also look at it this way as explained in section III.B.6.2.2 of the handbook: Economic capital is designed to absorb unexpected losses, which are equal to total losses at a given confidence level minus expected losses. (Expected losses are to be covered by credit reserves). Total losses are $100-$65=$35, and expected losses are 10%*$100=$10, therefore economic capital should be $35-$10=$25.)
NEW QUESTION 30
Which of the following are valid criticisms of value at risk:
I. There are many risks that a VaR framework cannot model
II. VaR does not consider liquidity risk
III. VaR does not account for historical market movements
IV. VaR does not consider the risk of contagion
- A. II and IV
- B. All of the above
- C. I, II and IV
- D. I and III
Answer: C
Explanation:
Explanation
Risks such as abrupt changes to a firm's business model caused by legislation, or the introduction of capital controls in foreign countries where a firm in invested, geo-political risks etc are not modelable in the traditional sense. These risks cannot be modeled using VaR. Therefore statement I is correct.
VaR indeed does not consider liquidity risk, it is only concerned with the standard deviation of portfolio returns. Statement II is a valid criticism.
Statement III is not correct, as VaR can consider historical price movements.
Statement IV is correct, as VaR does not consider systemic risk or the risk of contagion.
NEW QUESTION 31
Under the actuarial (or CreditRisk+) based modeling of defaults, what is the probability of 4 defaults in a retail portfolio where the number of expected defaults is 2?
- A. 4%
- B. 18%
- C. 2%
- D. 9%
Answer: D
Explanation:
Explanation
The actuarial or CreditRisk+ model considers default as an 'end of game' event modeled by a Poisson distribution. The annual number of defaults is a stochastic variable with a mean of and standard deviation equal to .
The probability of n defaults is given by (^n e^-) /n!, and therefore in this case is equal to (=2^4 * exp(-2))/FACT(4)) = 0.0902.
Note that CreditRisk+ is the same methodology as the actuarial approach, and requires using the Poisson distribution.
NEW QUESTION 32
......
A fully updated 2021 8008 Exam Dumps exam guide from training expert PassExamDumps: https://www.passexamdumps.com/8008-valid-exam-dumps.html
